India (NIFTY 50) P/E ratio, CAPE & earnings growth
Trailing and forward price-to-earnings ratios, CAPE and earnings for India, with history back to 1995. For the same measures across every major market see P/E ratios by country.
| Measure | Aug 2026 | Aug 2025 | Chg |
|---|---|---|---|
| Trailing P/E ratio | 21.76 | 22.61 | -0.85 |
| Forward P/E ratio | 19.86 | 21.50 | -1.64 |
| CAPE ratio | 29.83 | 33.88 | -4.05 |
Trailing P/E is aggregate market capitalisation divided by aggregate normalised net income over the previous twelve months. Forward P/E uses consensus estimates for the next twelve months.

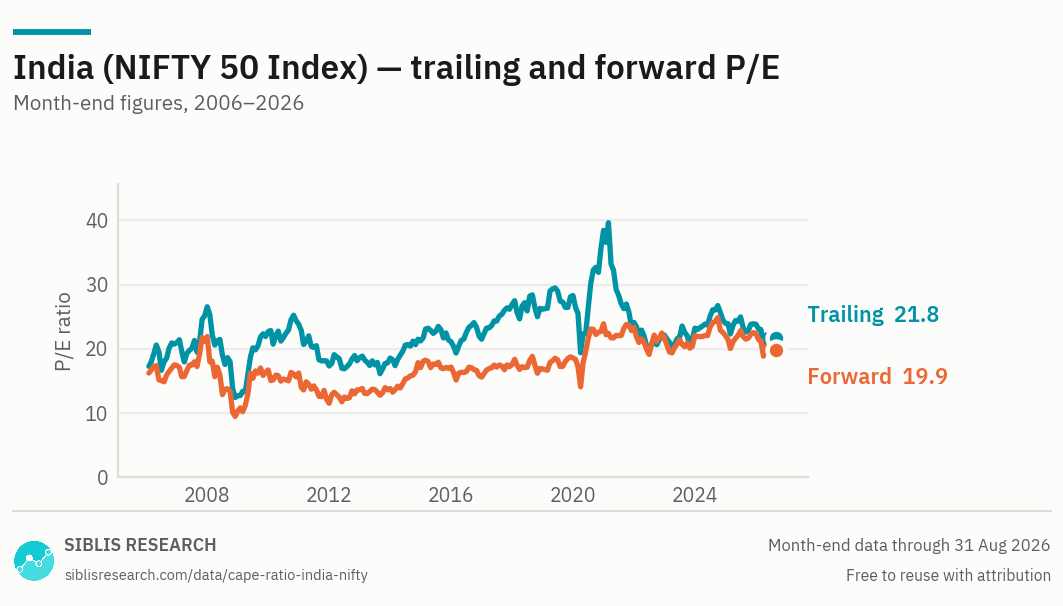
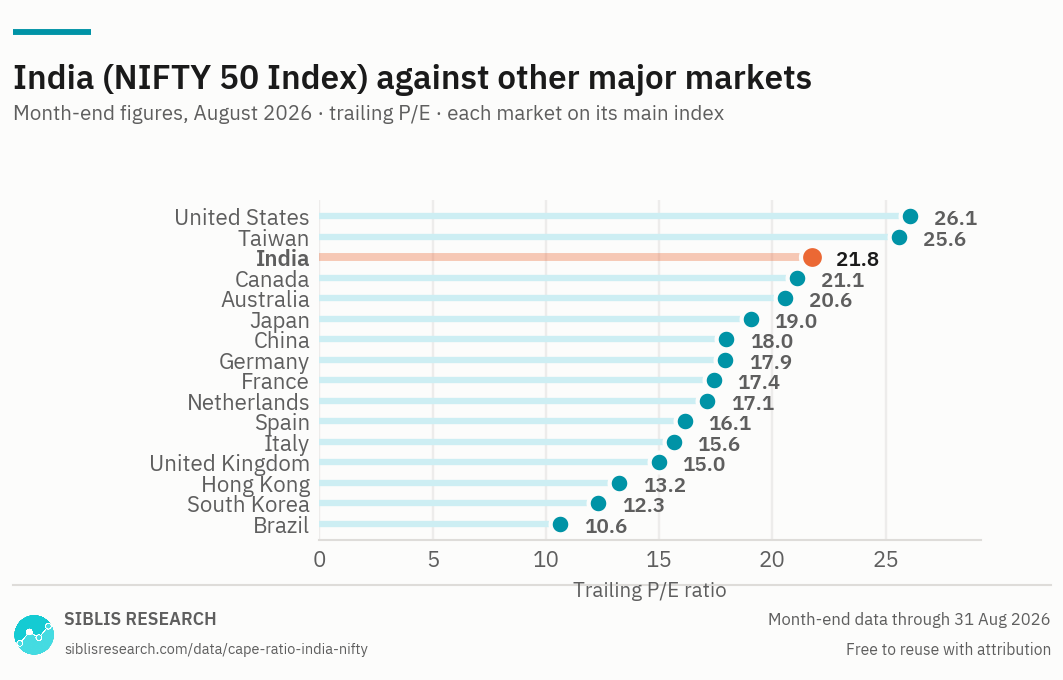
The 2007 peak is the reference point at the top of the Indian range. Position within a range is not the same as being cheap when the top of the range was a speculative episode.

| Month | Trailing P/E | Forward P/E | CAPE | EPS index |
|---|---|---|---|---|
| Aug 2026 | 21.76 | 19.86 | 29.83 | 290.5 |
| 2025 Dec | 23.83 | 22.38 | 35.09 | 287.8 |
| 2024 Dec | 23.96 | 22.05 | 34.09 | 259.0 |
| 2023 Dec | 23.22 | 22.03 | 34.87 | 245.7 |
| 2022 Dec | 22.13 | 21.69 | 32.42 | 214.8 |
| 2021 Dec | 24.11 | 23.32 | 34.77 | 189.0 |
| 2020 Dec | 38.45 | 23.90 | 29.91 | 95.5 |
| 2019 Dec | 28.30 | 18.58 | 27.49 | 112.9 |
| 2018 Dec | 26.17 | 16.86 | 25.86 | 109.0 |
| 2017 Dec | 26.92 | 17.56 | 25.33 | 102.7 |
| 2016 Dec | 21.49 | 15.59 | 20.21 | 100.0 |
Aug 2026 at a glance
Year on year
Where India stands, August 2026
India trades at 21.76 times trailing earnings, against 22.61 a year ago. Index earnings rose 2% over the year while the index itself fell 1%. The multiple barely moved, because earnings and price travelled together.
At 19.86 forward against a trailing 21.76, analysts are pricing a 10% rise in earnings over the coming twelve months. That is an expectation rather than a forecast with a track record, and the gap is worth reading as the size of what is being assumed.
Earnings growth that agrees with itself
India is one of the few markets where the one-year, three-year, five-year and ten-year earnings growth figures are all in the same range. This excludes the beginning of the COVID period when the P/E temporarily jumped as trailing earnings dipped. Index earnings have compounded at a broadly similar rate throughout.
That consistency is worth more than a single high growth rate. A market whose horizons agree is describing a trend; a market whose ten-year figure is far above its three-year figure is usually describing a recovery from a depressed base. Very few large markets look like the former.
The earnings growth page shows all the horizons together, which is where the comparison becomes visible.
The multiple has not really moved at all
Over ten years the Indian index and Indian index earnings have grown at close to the same rate, which means the multiple is roughly where it started. Whatever has driven Indian equities over the decade, an increase in what investors are willing to pay per unit of earnings is not the main part of it.
That is a different pattern from most markets that have risen as far.
A high multiple and a fast-growing denominator
India trades on one of the higher multiples among emerging markets, and on CAPE higher still. The CAPE reading in particular should not be read as a straight valuation signal: the measure divides price by ten years of average earnings, so a market whose earnings have grown quickly carries a structurally higher CAPE than a slow-growing one at the same price.
For how India sits inside the emerging markets index, see the emerging markets page.
Where this data is used
Some examples. Siblis valuation data appears in peer-reviewed journals, central bank publications and the financial press.
The whole database, every trading day
This page publishes one reading a month for 16 countries. The Global Equity Valuations Database is the whole thing.
How this is calculated
Aggregate market capitalisation of the index constituents divided by their aggregate earnings.
- Trailing P/E — Aggregate normalised net income over the previous twelve months. Major purely accounting gains and losses are removed.
- Forward P/E — Consensus estimates for the next twelve months, aggregated the same way.
- CAPE — Price divided by the average of ten years of inflation-adjusted aggregate earnings.
- Earnings — Shown indexed, to provide a common baseline. Index-level earnings per share in rupees are not comparable with other markets in level terms.
- Revisions — Figures are point-in-time. If a company later restates its results, the historic reading is left exactly as first published: the series reflects what was known at the time, not what is known now.
Cite this page
Siblis Research. (2026). India (NIFTY 50) P/E & CAPE Ratio [Data set]. Retrieved 31 August 2026, from siblisresearch.com/data/cape-ratio-india-nifty/
@misc{siblis_cape_ratio_india_nifty,
  title={India (NIFTY 50) P/E & CAPE Ratio}, author={{Siblis Research}},
  year={2026}, url={https://siblisresearch.com/data/cape-ratio-india-nifty/},
  urldate={2026-08-31}}
Charts on this page may be reproduced free of charge with attribution to Siblis Research and a link to this page.