NASDAQ 100 P/E ratio, CAPE and earnings growth
Valuation ratios and earnings growth for the NASDAQ 100, shown next to the four other U.S. indices carried here: large caps, small caps, growth and value.
The NASDAQ 100 trades at 34.24 times trailing earnings, against 26.08 for U.S. large caps. That is a ratio of 1.31, and the useful fact about it is not that it is above one. It is that the median since 1995 is 1.30 — the premium is close to its normal size, and has been for most of the past decade.
| Valuation | Earnings growth | ||||||
|---|---|---|---|---|---|---|---|
| Index | Trailing P/E | Forward P/E | Implied | CAPE | 1 year | 3 yr p.a. | 5 yr p.a. |
| NASDAQ 100 | 34.24 | 22.85 | +49.8% | 57.82 | +49.2% | +27.5% | +18.2% |
| U.S. Large Cap | 26.08 | 20.13 | +29.6% | 36.41 | +12.9% | +10.4% | +12.3% |
| Russell 2000 | 37.84 | 25.54 | +48.2% | 64.92 | +8.3% | +4.6% | +27.1% |
| Russell 1000 Growth | 35.60 | 23.27 | +53.0% | 53.43 | +20.9% | +19.2% | +11.7% |
| Russell 1000 Value | 22.48 | 16.83 | +33.6% | 25.73 | +14.3% | +5.2% | +5.4% |
Implied is the earnings growth the market has already priced in: trailing P/E divided by forward P/E, minus one. Earnings growth is the compound annual change in aggregate index earnings, nominal, not adjusted for inflation. All five indices are U.S. listings, so currency is not a factor in this table.

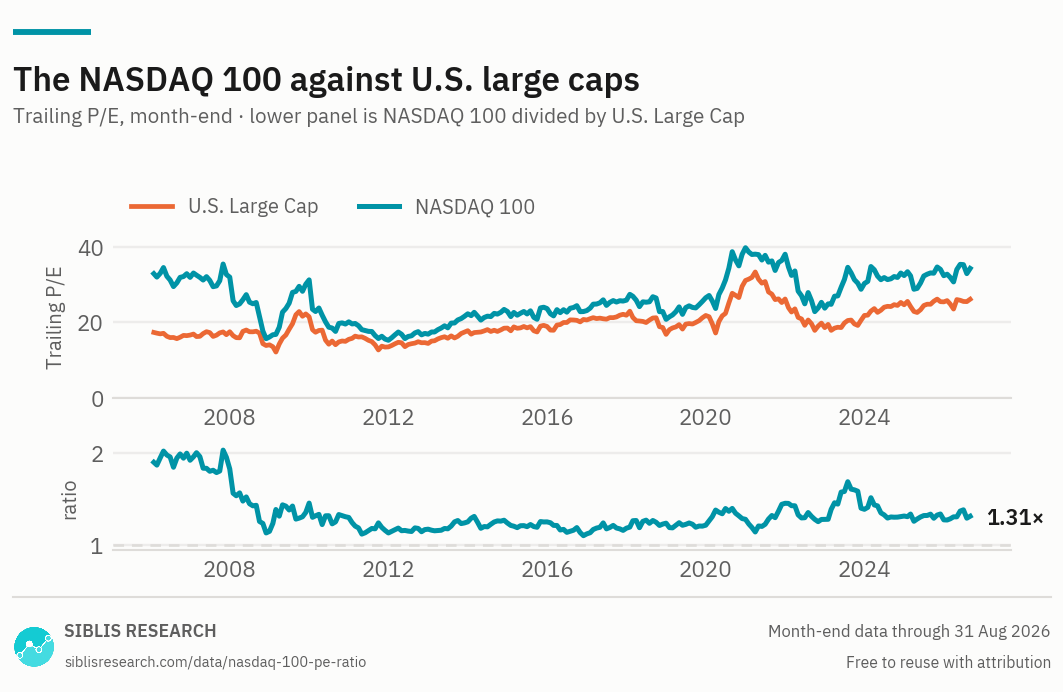
The lower panel is the part worth reading. The level of the NASDAQ 100 multiple moves with the market; the ratio between it and large caps moves with how differently investors are treating the two. Today's 1.31 against a median of 1.30 since 1995 puts the premium in the middle of its own range. The chart starts in 2006 because index earnings collapsed after the dot-com bust, sending the trailing multiple into the hundreds — a line containing that episode shows nothing else.

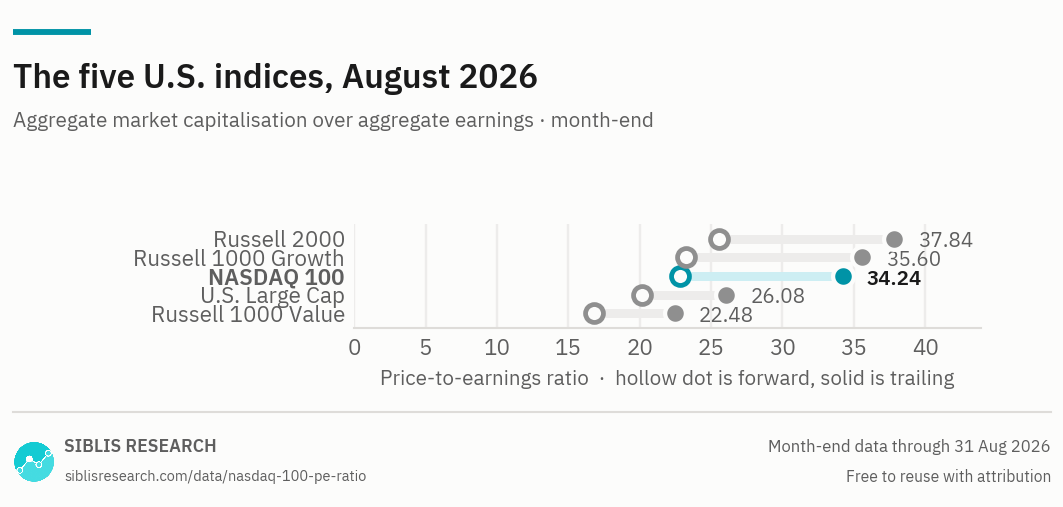
The hollow dot is the forward multiple and the solid dot the trailing one. The distance between them is the earnings growth analysts have priced into the coming twelve months — for the NASDAQ 100, +49.8%.
| Month | U.S. Large Cap | NASDAQ 100 | Russell 2000 | Russell 1000 Growth | Russell 1000 Value |
|---|---|---|---|---|---|
| Aug 2026 | 26.08 | 34.24 | 37.84 | 35.60 | 22.48 |
| 2025 Dec | 25.38 | 32.32 | 35.52 | 39.32 | 20.76 |
| 2024 Dec | 24.61 | 32.36 | 33.44 | 38.82 | 19.62 |
| 2023 Dec | 21.79 | 30.25 | 26.72 | 34.46 | 16.36 |
| 2022 Dec | 18.55 | 23.72 | 51.74 | 24.13 | 14.71 |
| 2021 Dec | 26.14 | 38.00 | 67.53 | 35.86 | 17.95 |
| 2020 Dec | 31.05 | 39.72 | Negative | 40.95 | 23.03 |
| 2019 Dec | 21.78 | 26.47 | 55.27 | 28.71 | 18.11 |
| 2018 Dec | 16.77 | 20.75 | 39.41 | 20.90 | 14.51 |
| 2017 Dec | 21.84 | 25.84 | 114.93 | 26.64 | 19.58 |
| 2016 Dec | 20.59 | 23.08 | 49.57 | 22.64 | 20.06 |
The complete series is part of the Global Equity Valuations Database.
NASDAQ 100, Aug 2026
Earnings, annualised
Where the NASDAQ 100 stands, August 2026
The index trades at 34.24 times trailing earnings, 22.85 times expected earnings and 57.82 times its ten-year average inflation-adjusted earnings. Aggregate index earnings grew +49.2% over the past year, +27.5% a year over three years and +18.2% a year over five — the fastest of the five indices on this page over one year and three years.
The headline multiple is high; the multiple against its own history is not
At 34.24 the NASDAQ 100 carries a higher trailing P/E than U.S. large caps or value. Read against its own record since 1995, the same reading sits at the 74th percentile — lower than U.S. large caps sit in theirs.
Both statements are true and they are about different things. The first says the index is expensive relative to the rest of the U.S. market, which it is and has been for most of thirty years, because its constituents grow earnings faster. The second says that premium has not widened. Over five years earnings grew +18.2% a year while the index itself rose +13.6% a year, so the multiple came down across that period rather than up. What the index has delivered came from the denominator, not from investors agreeing to pay more for it.
An aggregate multiple for a concentrated index is a statement about a few companies
The NASDAQ 100 is capitalisation-weighted and its largest constituents are among the largest companies listed anywhere. Because this ratio is aggregate market capitalisation over aggregate earnings, those companies dominate both the numerator and the denominator.
That matters for the forward figure in particular. The implied growth of +49.8% between the trailing and forward multiples is not a broad expectation about a hundred businesses; it is mostly an expectation about the handful at the top. Anyone using the number as a read on technology companies generally should look at the sector tables instead, where the weighting is different and the concentration is visible.
Characteristics of the index
The NASDAQ-100 is a stock market index that includes 100 of the largest non-financial companies listed on the NASDAQ stock exchange. Unlike the broader NASDAQ Composite, which includes thousands of stocks, the NASDAQ-100 focuses on large-cap growth companies, making it a key benchmark for tech-driven investment strategies.
The index is heavily technology-driven, but also includes companies from healthcare, consumer discretionary, and communication services. The index is dominated by the Magnificent Seven stocks who represent almost half of its total market cap.
For a style-based cut of the same market, the growth and value page splits U.S. large and mid caps on valuation characteristics rather than on where they are listed.
The U.S. index pages
All three carry the same five indices. What changes is which one is the subject, and the problem with the multiple that that index happens to show most clearly.
| Page | The question it answers | Why that one |
|---|---|---|
| NASDAQ 100 this page | What does the largest concentration of U.S. growth companies cost? | The index with the fastest earnings growth of the five, and the shortest CAPE history — which is the trap on that page. |
| Russell 2000 | Why do small caps carry a higher multiple than large caps? | An aggregate ratio nets the losses of unprofitable constituents against everyone else. Small caps are where that matters most. |
| Growth and value | How wide is the gap between growth and value, against its own history? | The same companies split by style rather than by size or listing venue, so the comparison is like for like. |
Where this data is used
Some examples. Siblis valuation data appears in peer-reviewed journals, central bank publications and the financial press.
The NASDAQ 100, every trading day
This page publishes one reading a month. The Global Equity Valuations Database is the whole dataset.
How this is calculated
Aggregate market capitalisation of the index divided by the aggregate earnings of its constituent companies — not an average of the constituents' individual multiples.
- Trailing P/E — Aggregate normalised net income over the previous twelve months. Major purely accounting gains and losses are removed.
- Forward P/E — Consensus estimates for the next twelve months, aggregated the same way.
- CAPE — Price divided by the average of ten years of inflation-adjusted aggregate earnings. Available from 2002, because the ten years of earnings history required for the first reading begin with the index itself.
- Earnings growth — Compound annual change in aggregate index earnings, nominal. Shown as n/a where earnings at the start of the period were negative.
- Coverage — The NASDAQ 100 from 1995 for the trailing multiple.
- Revisions — Figures are point-in-time. If a company later restates its results, the historic reading is left exactly as first published: the series reflects what was known at the time, not what is known now.
Cite this page
Siblis Research. (2026). NASDAQ 100 P/E ratio and earnings [Data set]. Retrieved 31 August 2026, from siblisresearch.com/data/nasdaq-100-pe-ratio/
@misc{siblis_nasdaq_100_pe_ratio,
  title={NASDAQ 100 P/E ratio and earnings}, author={{Siblis Research}},
  year={2026}, url={https://siblisresearch.com/data/nasdaq-100-pe-ratio/},
  urldate={2026-08-31}}
Charts on this page may be reproduced free of charge with attribution to Siblis Research and a link to this page.