Automobiles & Components valuation multiples
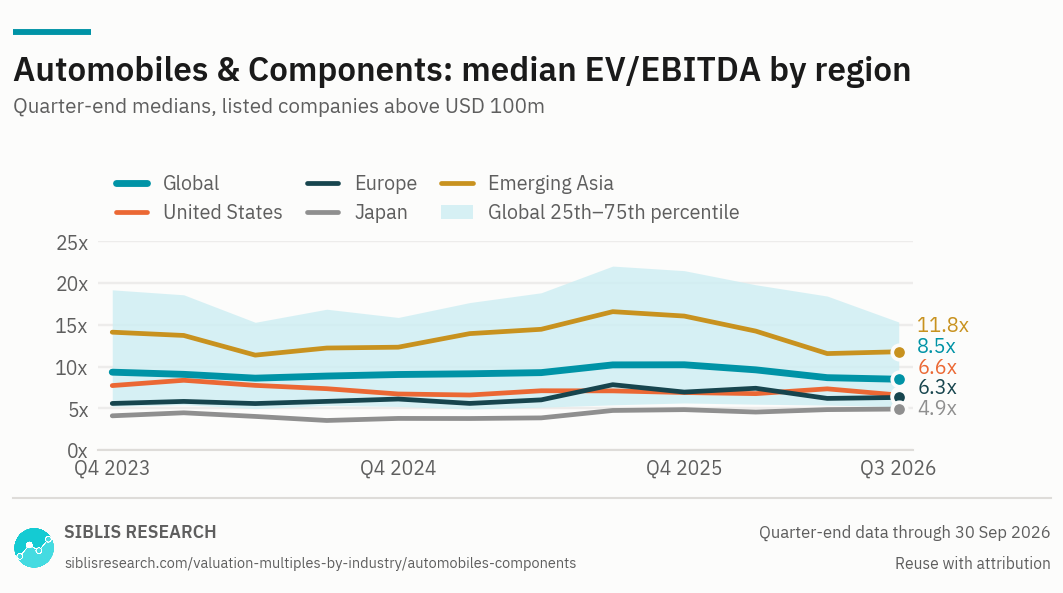
Worldwide, the median listed automotive company was valued at 8.5x EBITDA and 15.9x normalised earnings at 30 September 2026. By region, the median was 6.6x in the United States, 6.3x in Europe, 4.9x in Japan and 11.8x in Emerging Asia.
Global 505 listed automotive companies at 30 September 2026
median
median
median
median
*Excludes companies with negative EBITDA. **Excludes companies with negative normalised earnings. ***Excludes companies with stale accounts or results driven mainly by revaluations of investment holdings, and EV/Sales above 50x, typically early-stage companies with little revenue. How the figures are built
| EV/EBITDA | P/E | ||||
|---|---|---|---|---|---|
| Region | Companies | Median | Aggregate | Median | Aggregate |
| Global | 426 | 8.5x | 15.7x | 15.9x | 27.1x |
| United States | 27 | 6.6x | n/m | 12.7x | n/m |
| Europe | 40 | 6.3x | 7.2x | 13.0x | 11.1x |
| Japan | 59 | 4.9x | 5.8x | 11.2x | 12.0x |
| Emerging Asia | 286 | 11.8x | 9.4x | 20.5x | 19.6x |
Companies: those in the EV/EBITDA median. Median: the typical automotive company. Aggregate: the industry as a whole, total value over total revenue, earnings or book value, with larger companies weighing more and loss-makers included. Worldwide the larger companies trade on higher multiples than the typical one, so the aggregate sits above the median. In Emerging Asia it is the other way round, and the aggregate sits below the median. In the United States one company is so large a part of the industry that no aggregate is shown. n/m: not meaningful, or too few companies. How both are calculated
Valuation multiples by sector and region
What listed companies trade on worldwide, by region and sector, in ten pages. It may be shared and quoted with attribution to Siblis Research.
- Market multiples for eight regions: EV/EBITDA, P/E, EV/Sales, P/B
- 13 sectors by region: EV/EBITDA and P/E
- The most and least expensive industries
- Twelve quarters of history

| Multiple | Global | United States | Europe | Japan | Emerging Asia |
|---|---|---|---|---|---|
| EV/EBITDAEnterprise value to EBITDA; share-based pay counted as an expense. The key multiple for automotive companies. | 8.5x | 6.6x | 6.3x | 4.9x | 11.8x |
| P/ENormalised earnings: one-off items removed. | 15.9x | 12.7x | 13.0x | 11.2x | 20.5x |
| EV/SalesEnterprise value to revenue. | 1.2x | 0.8x | 0.7x | 0.6x | 1.6x |
| P/FCFMarket value to free cash flow. | 13.2x | 9.2x | 7.7x | 12.2x | 19.3x |
| Ratio | Global | United States | Europe | Japan | Emerging Asia |
|---|---|---|---|---|---|
| Gross margin | 18.7% | 19.2% | 19.5% | 18.6% | 18.6% |
| EBITDA margin | 10.9% | 9.6% | 10.5% | 11.2% | 10.9% |
| Revenue growth | 4.7% | 3.5% | −0.7% | 3.6% | 6.7% |
| SG&A to revenue | 8.7% | 9.8% | 7.8% | 12.2% | 5.8% |
Each ratio is the median of the companies that report the figure. Revenue growth compares the last twelve months with the twelve months before.
Global
- Tesla IncUS
- Toyota Motor CorpJapan
- BYD Co LtdChina
- General Motors CoUS
- Ferrari NVItaly
of 505 companies
United States
- Tesla IncUS
- General Motors CoUS
- Ford Motor CoUS
- Rivian Automotive IncUS
- BorgWarner IncUS
of 38 companies
Europe
- Ferrari NVItaly
- Porsche AGGermany
- Mercedes-Benz Group AGGermany
- Volkswagen AGGermany
- Bayerische Motoren Werke AGGermany
of 52 companies
Japan
- Toyota Motor CorpJapan
- Sumitomo Electric Industries LtdJapan
- Honda Motor Co LtdJapan
- Denso CorpJapan
- Bridgestone CorpJapan
of 62 companies
Emerging Asia
- BYD Co LtdChina
- Hyundai Motor Co LtdKorea
- Maruti Suzuki India LtdIndia
- Mahindra & Mahindra LtdIndia
- Kia CorpKorea
of 337 companies
Subscribers get the figures of all 505 companies at 30 Sep 2026, and of every company in earlier quarters, delisted ones included, with their key multiples, size band, last reporting date and data flags. Every median and aggregate can be checked company by company, and every company figure traced back to that company's own filings.
| Sub-industry | Covers | EV/EBITDA | P/E |
|---|---|---|---|
| Automobile Manufacturers | Cars, motorcycles, electric vehicles | See plans | See plans |
| Auto Parts & Tires | Auto parts, components and tires | See plans | See plans |
Global medians, 30 Sep 2026
Global median EV/EBITDA, 12 quarters
Automobiles & Components in the full data
One company and the aggregate
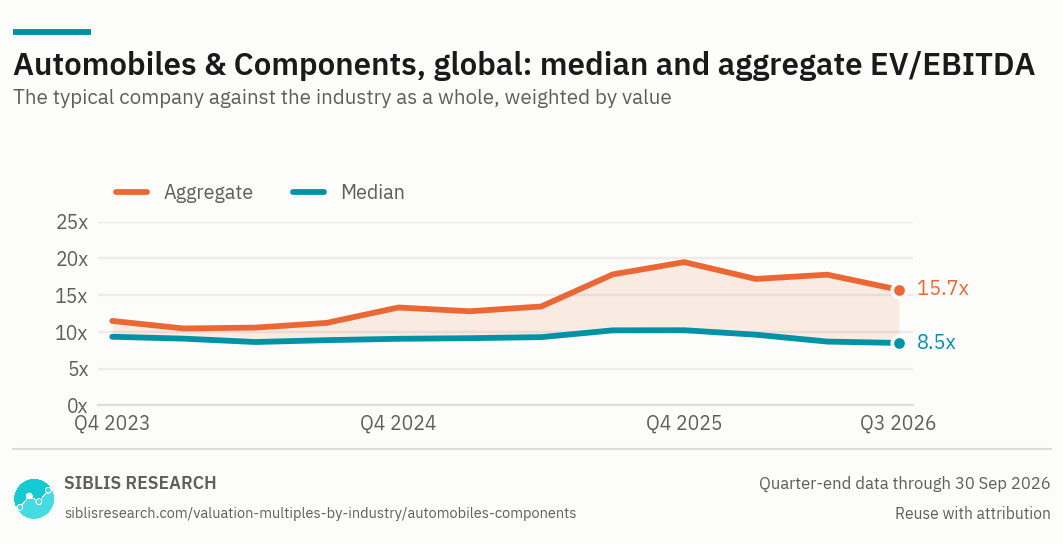
The global median EV/EBITDA is 8.5x, and the aggregate 15.7x. The gap is mostly one company. Tesla Inc is the largest company in the industry by value and trades far above every other carmaker; in the United States it is 85% of the industry's value, so no US aggregate is shown. Since Q4 2023 the global aggregate has risen from 11.5x to 15.7x, while the median has fallen from 9.3x to 8.5x.

By region
Emerging Asia has the highest median, 11.8x, with 230 of its companies in China. Japan has the lowest, 4.9x EBITDA and 0.6x revenue; Europe trades at 6.3x, on median revenue growth of −0.7%, and the United States at 6.6x.
Using these figures in a valuation
Carmakers and parts suppliers are valued differently, and a parts supplier's peer group should be other suppliers. For a carmaker with a finance arm, enterprise value includes the finance arm's debt and the multiple is not comparable with one without; the full data gives the companies behind each median, so the peer group can be checked.
What EV/EBITDA multiple do automotive companies trade at?
The median listed automotive company traded at 8.5x EBITDA (EV/EBITDA) at 30 September 2026, across 426 companies above USD 100m; the aggregate was 15.7x. United States 6.6x, Europe 6.3x, Japan 4.9x, Emerging Asia 11.8x.
What is the median P/E of automotive companies?
15.9x at 30 September 2026, across 362 companies; the aggregate was 27.1x.
Should a valuation use the median or the aggregate?
The median, with the 25th and 75th percentiles of a peer group close to the target in sub-industry and size. The aggregate describes the industry as an investor holding all of it would see it, and it is pulled towards the largest companies.
Do these figures include private automotive companies?
No. They cover listed companies with a market value above USD 100m. Data for US companies of USD 25–100m is available to subscribers as a separate universe.
Global Equity Valuations Database
- Question
- Is this market cheap or dear against its own history?
- Covers
- Stock market indices and their sectors, back to 1970 on the longest series
- Delivered
- Daily, through an API, with a monthly Excel dashboard
Siblis Global Valuation Multiples
- Question
- What does a company like my target trade on, and who are its listed peers?
- Covers
- 70 industries, 139 sub-industries and about 25,000 companies, delisted ones included
- Delivered
- Excel reports for every quarter end, licensed for client work
Every industry, at any valuation date
One subscription covers all 70 industries and 139 sub-industries in eight regions: about 25,000 companies, delisted ones included, at every quarter end since Q1 2009.
Siblis Research in research and the press
Siblis Research market valuation data appears in peer-reviewed journals, central bank publications and the financial press.
Companies with a market value above USD 100m whose main business is making cars, motorcycles and automotive parts, including tyres, listed on the largest stock markets in every region. Delisted companies are included for the dates they were listed, so past figures carry no survivorship bias.
Financial statements come from official filing databases where they exist, such as SEC EDGAR in the United States and EDINET in Japan, and otherwise from the companies' own published reports.
505 automotive companies at 30 September 2026. The number changes every quarter as companies list, delist or change industry. Companies with accounts more than about nine months old, and holding companies whose results are mainly revaluations of their investments, are left out.
The typical company: each counts once, from at least five values. A company with negative EBITDA, operating profit or normalised earnings is left out of the median of that multiple, as are multiples above 50x for EV/Sales or 100x for earnings multiples. So each median has its own number of companies.
The industry as a whole: total value over total revenue or earnings in US dollars, each company weighted by its free float, loss-makers included. Where one company is more than half the industry's value, the aggregate mostly describes that company; use the median.
Each figure uses only the financial statements public on the valuation date, over the last twelve months. Later restatements never change it.
Market value plus debt, preferred equity and minority interests, less cash. Lease liabilities are included on the IFRS 16 basis.
Restructuring, deal and litigation costs are added back; share-based pay stays an expense. Adjusted EBITDA adds share-based pay back as well.
Net earnings with one-off items removed, such as impairments, restructuring costs and disposal gains. The P/E uses these, never reported earnings.
Cite this page
Siblis Research (2026). Automobiles & Components Valuation Multiples [Data set]. Valuation date 30 September 2026. siblisresearch.com/valuation-multiples-by-industry/automobiles-components/
Charts on this page may be reproduced with attribution to Siblis Research and a link to this page.
@misc{siblis_automobiles_components_multiples,
  title  = {Automobiles & Components Valuation Multiples},
  author = {{Siblis Research}},
  year   = {2026},
  note   = {Valuation date 30 September 2026},
  url    = {https://siblisresearch.com/valuation-multiples-by-industry/automobiles-components/}
}