Health Care sector valuation
The U.S. health care sector trades at 24.67 times trailing earnings — higher than 87% of its readings since 1979 — and at 18.72 times the next twelve months of consensus estimates.
That step down is -24%, and it implies earnings +32% over a year. Aggregate earnings in this sector have grown 5.4% a year over five years and 7.4% over ten.
United States The four headline readings below are for the U.S. health care sector. The same six measures for the global and global ex-U.S. health care sectors are in the table that follows.
| Measure | United States | Global | Global ex-U.S. | U.S. premium |
|---|---|---|---|---|
| Trailing P/E | 24.67 | 22.42 | 18.40 | +34% |
| Forward P/E | 18.72 | 18.12 | 16.86 | +11% |
| CAPE | 26.99 | 25.97 | 23.82 | +13% |
| EV/EBITDA | 17.59 | 15.70 | 12.50 | +41% |
| Price to book | 5.64 | — | — | — |
| Dividend yield | 1.55% | — | — | — |
Global covers developed markets, emerging markets and the United States. Global ex-U.S. is the same universe with the United States removed, and still includes both developed and emerging markets. Dividend yield and price to book are published for the U.S. sectors only. Free to reuse with attribution.

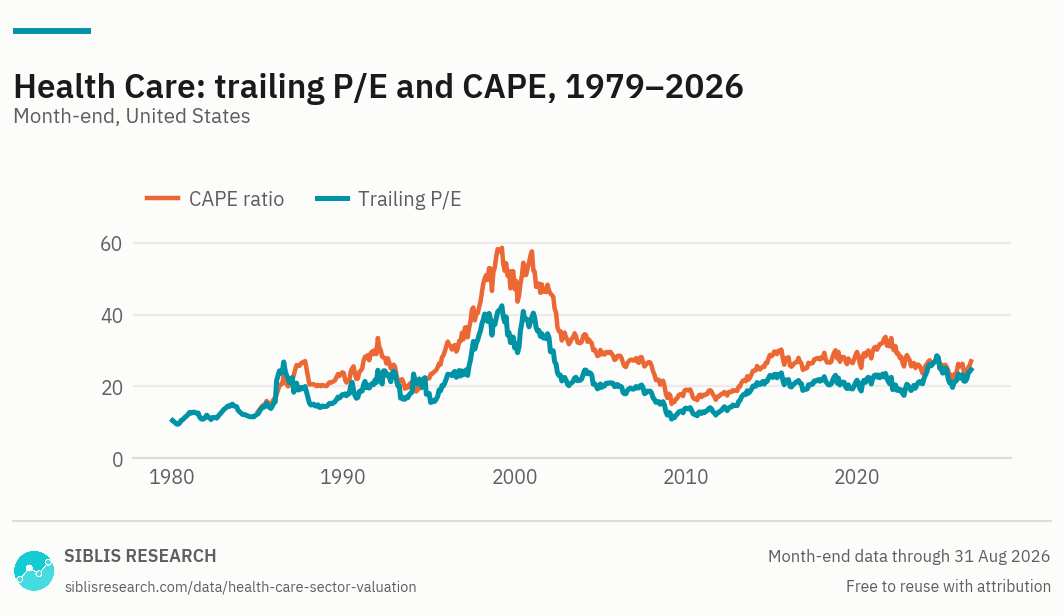
Trailing P/E and CAPE, U.S., from 1979. The lines run close together: current earnings are 1.09 times their own inflation-adjusted decade average, so the two measures are looking at almost the same denominator.

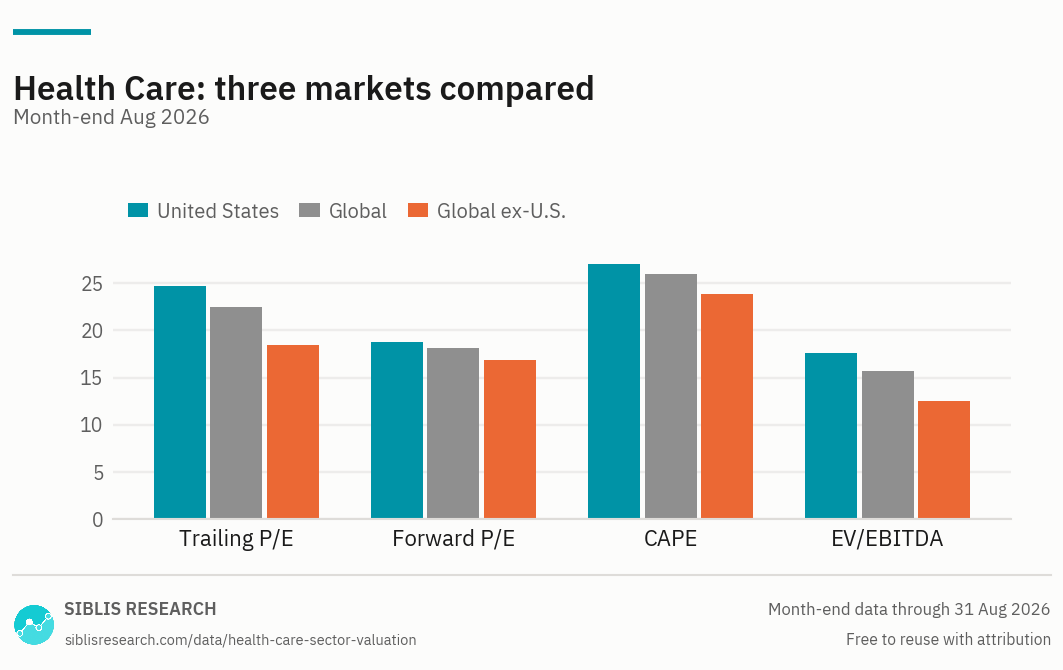
The same four measures, side by side in each market published. The American premium is wider on EV/EBITDA than on earnings.
| Year | Trailing P/E | CAPE |
|---|---|---|
| 2025 | 23.08 | 25.77 |
| 2024 | 23.71 | 24.38 |
| 2023 | 23.16 | 25.68 |
| 2022 | 20.19 | 27.95 |
| 2021 | 22.55 | 33.45 |
| 2020 | 23.01 | 30.77 |
| 2019 | 21.74 | 29.61 |
| 2018 | 20.39 | 26.87 |
| 2017 | 21.78 | 27.82 |
| 2016 | 19.21 | 24.97 |
The full monthly history from 1979, the dividend yield and price-to-book series, and the global and global ex-U.S. figures are available to subscribers.
United States, Aug 2026
U.S. sector against its own history
The two multiples disagree about where this sector is
The trailing P/E of 24.67 sits at the 87th percentile of its history since 1979. CAPE, at 26.99, sits at the 54th percentile of a history starting in 1984. Expensive on one, ordinary on the other.
Usually that gap means earnings are far from their decade average — high, as in a commodity upswing, or low, as after a collapse. Here they are not. The ratio of CAPE to the trailing P/E is 1.09: current earnings sit barely above their own inflation-adjusted ten-year average.
So the two measures are being applied to almost the same denominator, and the divergence is doing something more specific. The P/E is high relative to its own past because the sector has become more expensive relative to what it earns. CAPE is unremarkable because the decade being averaged was itself strong. Both are true, and the second is the reason the first is easy to under-react to.
What the forward multiple is pricing
A forward P/E below a trailing P/E is normal: estimates for next year are almost always higher than last year's results, in every sector and in most years.
The size of the step is what varies. Here it is -24%, which is the same thing as saying the market is priced for aggregate earnings +32% higher twelve months out. Against that: the last twelve months delivered 5.8%, the five-year rate is 5.4% a year and the ten-year rate is 7.4%.
The gap between what is implied and what has been delivered is the honest summary of this page. It does not make the estimates wrong — sector earnings do sometimes jump, and a single year is not a trend — but it does mean that a reader treating the forward P/E as the sector's "real" valuation is accepting a growth assumption well outside anything in the recorded history, rather than sidestepping one.
One methodological caution, because it cuts the other way. Our trailing earnings are normalised: major purely accounting gains and losses are removed. Consensus estimates are compiled on whatever basis the contributing analysts use. Where those two definitions differ, some of the step is arithmetic rather than expectation, so it should be read as a direction and a rough magnitude rather than as a precise forecast.
The steadiest earnings in the market
In the 524 months since 1979 where a year-on-year comparison is possible, aggregate earnings in this sector were below their year-earlier level 16% of the time — the fewest of the eleven sectors. The worst twelve-month fall on record is -25.5%, in April 1994.
That consistency is the case for the multiple, and it is a real case. It is also the reason the CAPE reading deserves weight here even though it is the less flattering of the two: a ten-year average is a poor denominator for a sector whose earnings swing wildly, and a good one for a sector whose earnings do not.
Consumer staples reaches a similar place from the other direction — the mildest worst year of the eleven, and the slowest growth.
The American premium, and what it is not
U.S. health care trades +34% above the rest of the world on trailing earnings, +13% on CAPE and +41% on EV/EBITDA.
The EV/EBITDA premium being the widest of the three points at the balance sheet: on a whole-company basis, including debt, the American sector costs more relative to what it earns than the equity-only comparison suggests.
The CAPE premium being the narrowest points somewhere else. Measured against their own decade of earnings, the American and international sectors are much closer than measured against each other. Most of the gap on current earnings is a gap in what has happened over the last ten years, not a standing difference in what the market will pay.
Choosing a measure
No single ratio answers every question about a sector. Each of these pages covers the same eleven sectors — what changes is the question the measure is good at, and how far the coverage reaches.
| Measure | The question it answers | Why that one |
|---|---|---|
| EV/EBITDA | How does one sector compare across markets? | Sits above tax and debt, so it survives crossing borders. The only measure here that makes an international sector comparison sound. |
| P/E and earnings | How fast are a sector’s earnings growing? | Trailing and forward multiples with the earnings behind them, so the multiple and its denominator can be read together. |
| CAPE | Is a sector expensive against its own history? | Averages a decade of real earnings, which smooths the cycle out of the denominator. |
| Price to book | What is the market paying for the assets? | Works where earnings-based measures break down — asset-heavy sectors, and banks in particular. U.S. sectors only. |
| Dividend yield | Which sectors pay, and how much? | Income rather than valuation, but it moves inversely with price and is read alongside the multiples. U.S. sectors only. |
Communication Services · Consumer Discretionary · Consumer Staples · Energy · Financials · Industrials · Technology · Materials · Real Estate · Utilities
All eleven side by side: sector valuations. To compare them on one measure: P/E and earnings · CAPE ratios · EV/EBITDA · Dividend yields · Price to book.
Where this data is used
Some examples. Siblis valuation data appears in peer-reviewed journals, central bank publications and the financial press.
The whole health care history, every trading day
This page publishes ten year-ends and the current reading. The database carries every month back to 1979, for all eleven sectors and every market.
How this is calculated
Every ratio is calculated on the aggregate: the total market capitalisation of the sector's constituents divided by their aggregate earnings, book value or EBITDA, rather than as an average of the constituents' own ratios.
- Trailing P/E — Aggregate normalised net income over the previous twelve months. Major purely accounting gains and losses are removed.
- Forward P/E — Consensus estimates for the next twelve months, aggregated the same way. Estimates are compiled on their own basis, which need not match the normalisation applied to trailing earnings.
- CAPE — Price divided by the average of ten years of inflation-adjusted aggregate earnings.
- Earnings growth — Calculated on aggregate sector earnings, not a per-share figure, so it is unaffected by buybacks. The one-year figure compares two month-ends. Rates over five years and longer compare the average of the twelve months at each end, so that one unusual month at the start does not set the whole rate.
- Coverage — U.S. series from 1979; global and global ex-U.S. from 1997. Dividend yield and price to book are U.S. only, from 2005 and 1979. The universes are comparable as levels but not as history, because they do not span the same period.
- Percentiles — The share of month-ends in that series' own history with a lower reading than the current one.
- Revisions — Figures are point-in-time. If a company later restates its results, the historic reading is left exactly as first published.
Cite this page
Siblis Research. (2026). Health Care sector P/E, CAPE and EV/EBITDA — U.S. and global [Data set]. Retrieved 31 August 2026, from siblisresearch.com/data/health-care-sector-valuation/
@misc{siblis_health_care_sector_valuation,
  title={Health Care sector P/E, CAPE and EV/EBITDA — U.S. and global}, author={{Siblis Research}},
  year={2026}, url={https://siblisresearch.com/data/health-care-sector-valuation/},
  urldate={2026-08-31}}
Charts on this page may be reproduced free of charge with attribution to Siblis Research and a link to this page.